
Important Things to Keep in Mind Before Applying for a Loan
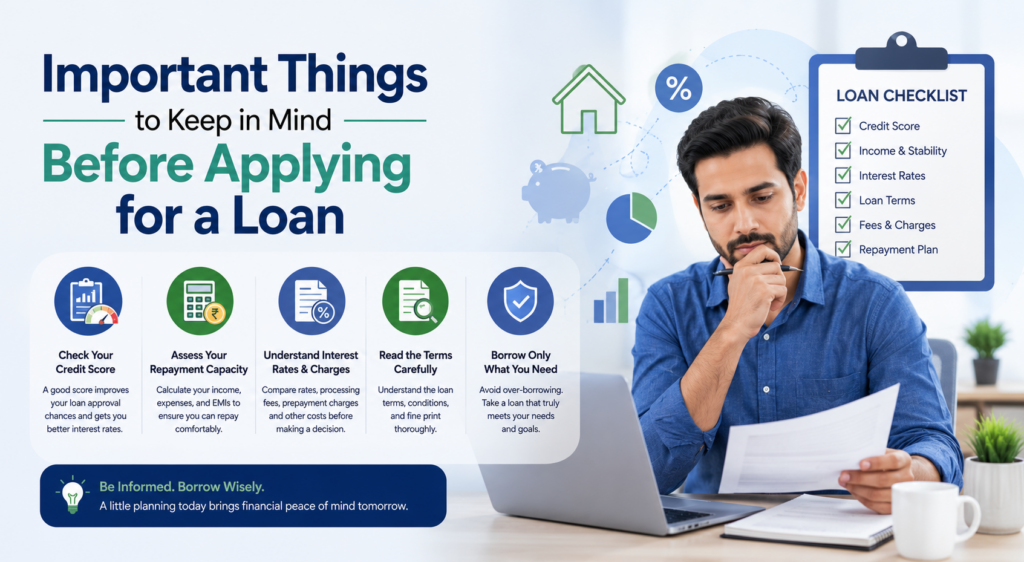
Taking a loan can help you achieve important goals like buying a home, funding education, or handling emergencies. However, applying without proper planning can lead to financial stress. This guide explains the most important things you should keep in mind before applying for any loan. 1. Understand Why You Need the Loan Before borrowing, ask: Is the loan necessary? Can I delay the expense? Can I manage repayments comfortably? Avoid taking loans for unnecessary luxury spending. 2. Check Your Credit Score Your credit score is one of the most important factors lenders consider. Benefits of a Good Credit Score Faster approval Lower interest rates Higher loan eligibility Ways to Improve Score Pay EMIs on time Clear credit card dues Avoid loan defaults 3. Calculate Your EMI in Advance Never apply without knowing your monthly repayment amount. EMI Should Fit Your Budget Financial experts suggest: Total EMIs should stay below 40–50% of income Financial Planning Tips This helps maintain financial stability. 4. Compare Multiple Lenders Different lenders offer different loan terms. Compare: Interest rates Fees Repayment flexibility Approval speed Research helps save money. 5. Read Terms and Conditions Carefully Many borrowers ignore the fine print and later face problems. Always check: Penalty charges Foreclosure fees Processing charges Insurance requirements Never sign documents blindly. 6. Borrow Only What You Need Higher loan amounts mean: Bigger EMIs More interest Longer debt burden Borrow responsibly. 7. Keep Documents Ready Having documents prepared speeds up approval. Important Documents Aadhaar Card PAN Card Salary slips Bank statements Income proof 8. Avoid Multiple Applications Applying to many lenders simultaneously can: Lower credit score Make you appear credit-hungry Instead, check eligibility first. 9. Check Your Debt-to-Income Ratio Banks evaluate your existing financial obligations. Debt-to-Income Ratio Formula Debt-to-Income Ratio=Total Monthly DebtMonthly Income×100\text{Debt-to-Income Ratio} = \frac{\text{Total Monthly Debt}}{\text{Monthly Income}} \times 100Debt-to-Income Ratio=Monthly IncomeTotal Monthly Debt×100 A lower ratio improves approval chances. 10. Plan for Emergencies Unexpected situations like job loss or medical emergencies can affect repayments. Maintain: Emergency savings Backup income source This prevents loan default. Common Loan Application Mistakes Submitting incorrect documents Ignoring credit score Taking excessive loans Not comparing lenders Missing EMI calculations Final Thoughts Loans can be helpful financial tools when used wisely. Proper planning before applying helps you secure better interest rates, avoid rejection, and maintain healthy finances. Always borrow responsibly and choose loans that match your repayment capacity.
Important Things to Keep in Mind Before Applying for a Loan Read More »